Recurring Payments, Reconsidered: A Household Audit for 2026
A standing order is a small instruction with a long memory. It leaves an account on the same date, in the same amount, often for years after the reason for it has faded. The same is true of many direct debits. Individually they are modest; together they can amount to a quiet second budget that no one consciously agreed to.
An audit of these commitments is not an exercise in austerity. It is an exercise in alignment. The purpose is to establish what is being paid, why it is being paid, and whether the answer still holds for the household as it is in 2026, rather than as it was when the payment began.
Begin with the raw evidence
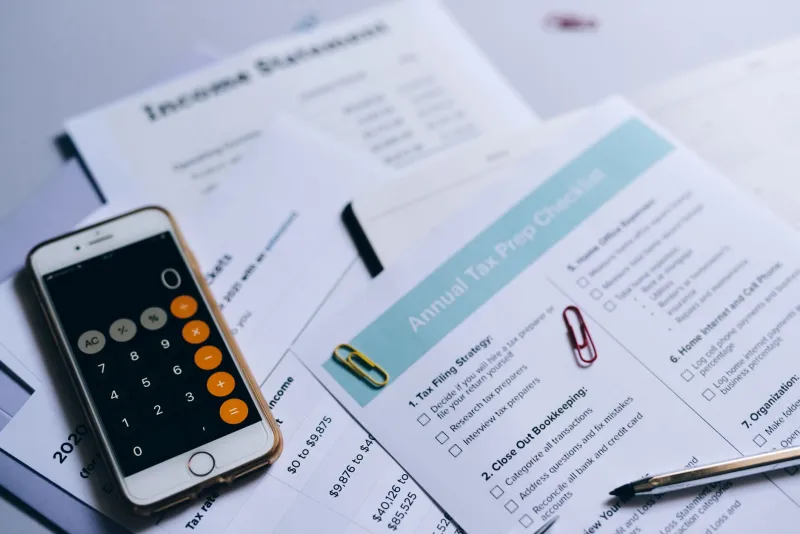
Start with twelve months of statements for every current account, including any joint account. Highlight each payment that recurs. Do not rely on memory or on a budgeting app alone; the statements are the record. Build a simple list with five columns: payee, amount, frequency, approximate start date if known, and what the payment was originally intended to achieve.
This first pass should be deliberately unselective. Include insurance premiums, savings transfers, pension contributions, subscriptions, memberships, professional fees and anything else that arrives with regularity. Some will be direct debits collected by an organisation; others will be standing orders the household controls. Both deserve the same scrutiny.
Sort by function rather than by habit
Once the list is complete, group the payments by function. Protection policies form one group. Savings and investment contributions form another. Pension payments, whether to a workplace scheme or a personal arrangement, form a third. Subscriptions, memberships and household services can be grouped together. The categories matter less than the act of seeing the commitments side by side.
A common pattern emerges. Some payments are essential and well understood. Others are modest but duplicated. A few are inherited from an earlier stage of life and have never been reviewed. The audit should not assume that any of these is wrong. It should simply place each one in a position to be judged on its merits.
Four questions for every commitment
For each payment, apply the same four tests.
Cost. Is the amount still proportionate to the benefit received? Has it risen quietly through annual increases? For insurance, has the premium moved in line with cover, or has cover stayed still while the price climbed? For subscriptions, is the current price still competitive?
Cover. For protection policies, what is actually insured? Is the sum assured adequate for current liabilities and family circumstances? Are there exclusions or conditions that would matter at the point of claim? For non-insurance payments, what service or benefit is received, and is it still used?
Tax treatment. Is the payment being made from the right pot? Contributions to pensions, ISAs and protection policies can carry different tax consequences. A payment that was efficient when it began may now sit less comfortably with the household’s overall position. This is not a reason to act hastily, but it is a reason to ask the question.
Long-term value. Does the payment support a goal the household still holds? Would it be started again today, on the same terms, if it did not already exist? A yes is a useful answer. A no is equally useful, because it opens the door to a decision.
Three outcomes: keep, renegotiate or cancel
After the four questions, each payment should fall into one of three broad outcomes.
Keep. The commitment still meets a need, remains competitively priced and fits the household’s longer-term plan. Keeping it is an active decision, not a passive one.
Renegotiate. The need remains, but the terms do not. This might mean adjusting cover, changing a contribution, comparing providers or asking for a better rate. Renegotiation is often the most productive outcome because it preserves the benefit while improving the terms.
Cancel. The payment no longer serves a purpose, duplicates another arrangement or has been forgotten altogether. Cancellation should be confirmed in writing where possible, and any associated cover or benefit should be checked before the payment stops.
A note on protection policies
Old protection policies deserve particular care. A life assurance policy taken out for a former mortgage may no longer match the liability it was designed to cover. A critical illness policy may have been arranged before a change in circumstances. An income protection policy may have terms that are difficult to replicate today.
Before cancelling any protection policy, establish what would be lost. Premiums, cover, ownership and beneficiary arrangements all matter. In some cases the right move is to keep the policy and adjust elsewhere; in others it is to replace it with something more suitable. The audit should inform that decision, not pre-empt it.
Savings and pension contributions
Small standing orders into savings accounts or personal pensions are easy to set up and easy to overlook. Check the interest rate on savings and the platform or fund charges on investments. A modest pension contribution may attract tax relief, and it is worth confirming that relief is being claimed correctly. For the self-employed, the question of whether contributions are being made at all is often as important as the amount.
Put the next review in the calendar
An audit is most useful when it is repeated. Choose a fixed date each year, keep a one-page summary of the commitments that remain, and revisit the list after any significant life event. The aim is not to eliminate regular payments but to ensure that each one is still a promise the household intends to keep.
Clear guidance for long-term money decisions begins with seeing the whole picture. Nixon Financial Services encourages a measured approach: gather the evidence, ask the same questions of every commitment, and let the answers decide what stays.